Yes, you can generally get or manage a home loan while on maternity or parental leave in Australia, provided you can document a return-to-work plan or show enough household income to cover repayments. Start by gathering your employer's return-to-work letter and evidence of your parental leave payments. Lender policies vary widely, so shopping around or working with a broker matters more here than in almost any other lending scenario.
TL;DR:
- Most lenders assess parental leave applications based on household income and a confirmed return-to-work date, not on the fact of being on leave alone.
- Having a return-to-work letter, recent payslips, and parental payment statements ready can significantly improve approval chances.
- Options like interest-only periods, repayment holidays, and loan extensions can ease cashflow during leave but may increase total interest paid.
- Applying for a new loan while on unpaid leave is more difficult and often relies on a co-borrower's stable income or a substantial savings buffer.
- Engaging a mortgage broker can help match your specific leave situation with a lender's policies, simplifying paperwork and increasing approval likelihood.
Table of Contents
- What repayment options do lenders offer during parental leave?
- Can you apply for a new loan while on leave?
- What paperwork do lenders want from parents on leave?
- How can you strengthen your application while on leave?
- What if you can't keep up with repayments?
- How does a broker help parents on leave choose the right lender?
- The paperwork matters more than the policy
- Get your paperwork reviewed before you apply
- Where to verify the details
- Sources
- FAQ
What repayment options do lenders offer during parental leave?
Most major lenders offer several ways to ease cashflow pressure once income drops, and the right choice depends on how much buffer you've already built into the loan.
If you've been making extra repayments, redraw and offset accounts are usually your first port of call. Drawing down a redraw balance or letting an offset account absorb reduced income buys time without changing your loan terms.
Beyond that, NAB's parental leave guidance outlines the temporary measures many lenders will consider:
- Interest-only periods, which lower monthly repayments but don't reduce the principal.
- Reduced minimum repayments for a set window, usually reassessed after a few months.
- Repayment holidays, sometimes running from two to twelve months depending on eligibility and the lender's policy.
- Loan term extensions, which spread the balance further but increase total interest paid.
- Refinancing, worth considering if your current lender's parental leave policy is rigid. A loan comparison calculator helps you see whether switching actually saves money once fees are factored in.
Fixed-rate loans complicate things slightly. Break costs can apply if you refinance mid-term, so check your contract before assuming a switch is free.
Can you apply for a new loan while on leave?
Lenders in Australia are required to assess your ability to repay a loan, not your parental status, and discriminating against applicants on the basis of pregnancy or parental leave is unlawful. That doesn't mean every application sails through. It means the assessment has to focus on income, evidence, and serviceability rather than the fact that you're currently off work.
Paid parental leave payments, including the government scheme detailed by Fair Work, can be counted as income for serviceability purposes, though most lenders treat it as temporary rather than ongoing.
Key factors that shape how a lender views your application:
- Whether Centrelink parental leave pay or employer-paid leave, as outlined on Services Australia's payment page, is being received.
- Whether you have a verified return-to-work date confirmed in writing by your employer.
- Whether your leave is paid or unpaid. Unpaid leave carries more risk in a lender's eyes, and a co-borrower's income becomes far more important in that case.
- Whether a partner or co-borrower has stable income that can carry the loan on its own if needed.
Lenders that will accept future return-to-work income tend to want firm, dated confirmation, not a vague intention to go back "sometime."
What paperwork do lenders want from parents on leave?
The paperwork is where most parental leave applications stall, not the policy itself. Get these documents ready before you approach a lender or broker:
- Employer return-to-work letter, stating your role, contracted hours, salary, and confirmed return date.
- Recent payslips and tax returns covering the period before your leave started.
- Centrelink or parental leave payment statements showing the amount and duration of payments received.
- Bank statements, including evidence of any redraw or offset balance you're holding as a buffer.
- Partner or co-borrower income proof, such as payslips or a letter from their employer.
- For casual or self-employed borrowers: an ABN, profit-and-loss statements, BAS lodgements, and recent tax returns, since timing here can decide which lenders will even consider the application.
Our home loan documents guide breaks down common red flags lenders flag during this checklist stage.
Pro Tip: Ask your employer to state the exact return date, expected hours, and salary in the letter. Stay at Home Mum reports that vague letters missing these three details are one of the most common reasons parental leave applications get stuck.
How can you strengthen your application while on leave?
A few deliberate moves can shift a borderline application into an approved one.
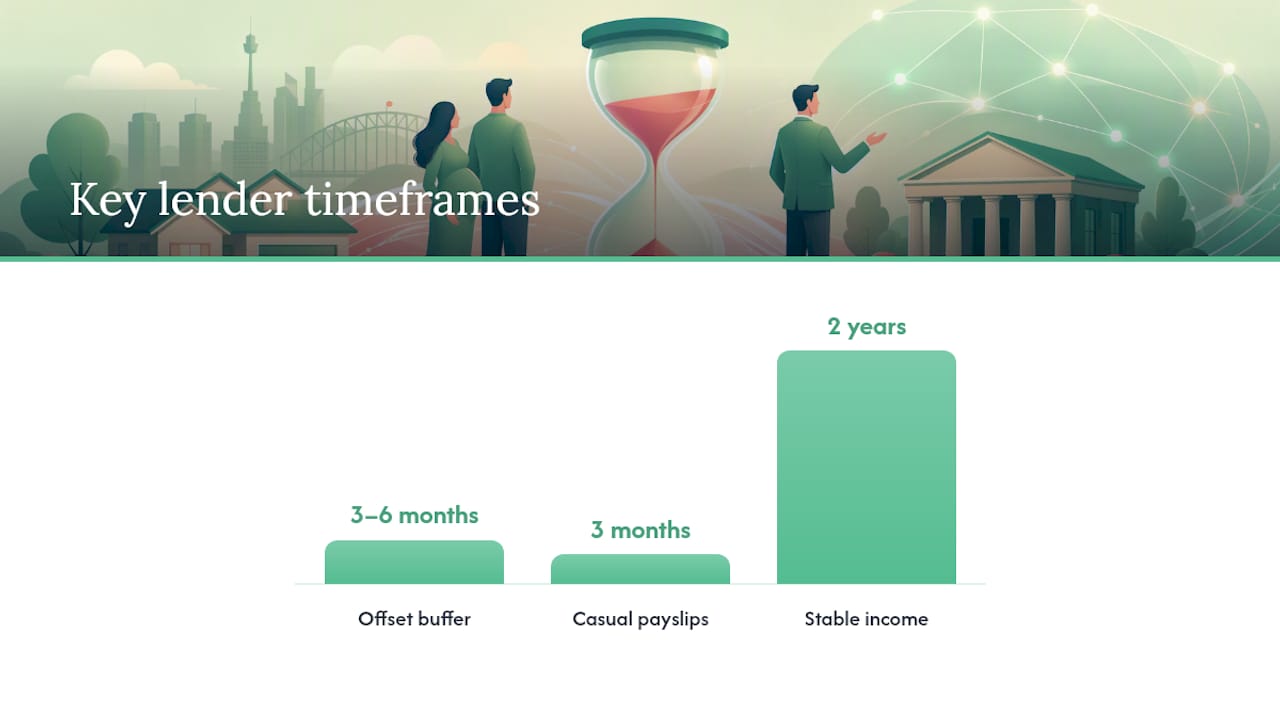
Get the employer letter right the first time. Omitting the return date or listing "casual hours" instead of a firm figure is the single most avoidable mistake applicants make. Build a visible cash buffer in the months before you apply, ideally three to six months of repayments sitting in an offset account, and pay down any discretionary debt like car loans or credit cards that eat into your serviceability.
- Consider a joint application with a partner whose income is stable and ongoing.
- A guarantor can help if your household income alone doesn't meet a lender's threshold.
- Time settlement to land either before leave starts or after a confirmed return date, whichever suits the lender's rules better.
- Compare lenders rather than assuming your current bank's policy is the most flexible one.
Pro Tip: A broker who knows individual lenders' rulebooks can save weeks of back-and-forth, because some lenders accept three months of casual payslips while others insist on two years of stable income before they'll even look at a file.
What if you can't keep up with repayments?
Contact your lender before you miss a payment, not after. Most banks have a hardship team that can arrange a temporary payment plan, a short repayment pause, or a switch to interest-only, exactly the options NAB describes for parental leave borrowers.
Understand the trade-offs before you agree to anything:
- Interest usually keeps accruing during a repayment pause, so the balance grows even while you're not paying.
- Some lenders restrict redraw access once a hardship arrangement is in place.
- Repayments after the pause ends can be higher than before, to make up the shortfall over a shorter remaining term.
Moneysmart's guide to returning to work after having a baby is worth reading for broader budgeting strategies during this stretch, and it's also worth checking whether any Centrelink entitlements you're eligible for haven't been claimed yet. If the numbers still don't add up, a financial counsellor or broker can help you weigh whether a hardship variation, refinance, or loan term extension makes more sense for your situation.
How does a broker help parents on leave choose the right lender?
Every lender treats parental leave differently: some cap how much of a parental payment they'll count as income, others want a return-to-work date confirmed months in advance, and a few barely blink at unpaid leave if the household buffer is solid. A broker's real value is matching your specific leave type, income mix, and timeline to the lender whose rulebook actually fits, rather than the one you happen to already bank with.
Some brokers offer practical tools such as offset and repayment calculators to model different leave scenarios before commitment; dedicated mortgage relationship managers who review paperwork and flag gaps early; and strategy sessions that explore which lenders suit casual, self-employed, or dual-income households.
Expect a broker appointment to start with a straightforward paperwork review, and expect full transparency about how brokers are paid, typically a commission from the lender on settlement, not a fee charged to you. Our introduction to mortgage brokers covers this in more detail if you're weighing whether a broker is worth involving.
The paperwork matters more than the policy
Most articles on this topic focus on which lender has the "best" parental leave policy, as if there's a single winner. That's the wrong question. The real determinant of approval is whether your paperwork removes doubt, not whether you picked the theoretically most generous lender.
An employer letter with a firm return date and salary figure will often outperform a marginally better lender policy paired with vague documentation. Conventional advice tends to underweight this, treating the letter as a formality rather than the decisive piece of evidence it often is.
If there's one thing to prioritise first, it's timing your paperwork collection before you need it, not scrambling once your leave has already started. Get the return-to-work letter drafted properly, gather your payment statements, and build whatever buffer you can in the months beforehand. Lender selection matters too, but it's the second decision, not the first.
— Allen
Get your paperwork reviewed before you apply
Using a mortgage broker gives parents on leave access to expertise about which lenders accept a return-to-work letter over extensive payslips and which have stricter requirements. Instead of navigating lender policies alone, a mortgage relationship manager reviews your documents against lender criteria before submission.

Start by running your numbers through our home loan offset calculator to see how a buffer affects your repayments, then book a session with our mortgage relationship manager for a paperwork review. Brokers are paid by the lender on settlement, not by you, and that initial review is typically the first and only step needed to find out where you stand.
Where to verify the details
For the legal framework around paid parental leave, check Fair Work's parental leave page. Services Australia's parental leave pay page confirms entitlements. Moneysmart's having a baby hub has budgeting calculators, and Savings covers what lenders assess case by case.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Paid parental leave — Fair Work
- Returning to work after having a baby — Moneysmart
- Manage your home loan repayments while on parental leave — NAB
- Savings
FAQ
Can I get a mortgage if I'm on maternity leave?
Yes, most lenders will assess an application from someone on maternity leave provided you can show a return-to-work letter, parental payment evidence, or sufficient household income to cover repayments.
Can I get a loan while on parental leave if I'm unpaid?
It's harder but not impossible. Unpaid leave usually means the lender leans heavily on a co-borrower's income or a strong savings buffer, since your own income can't be counted as ongoing.
What benefits are available for parental leave in Australia?
Eligible parents can access the government's paid parental leave scheme through Fair Work, plus Centrelink entitlements detailed on the Services Australia payments page.
How much parental leave support does NAB offer borrowers?
NAB's parental leave policy for existing home loan customers can include repayment holidays of around two to twelve months, depending on eligibility, alongside interest-only options and reduced repayment arrangements, as outlined on NAB's parental leave page.
Should I use a broker or apply directly while on leave?
A broker can match your leave type and income mix to lenders whose policies genuinely suit your situation, which often saves time compared with approaching a single bank directly and hoping their rules fit.